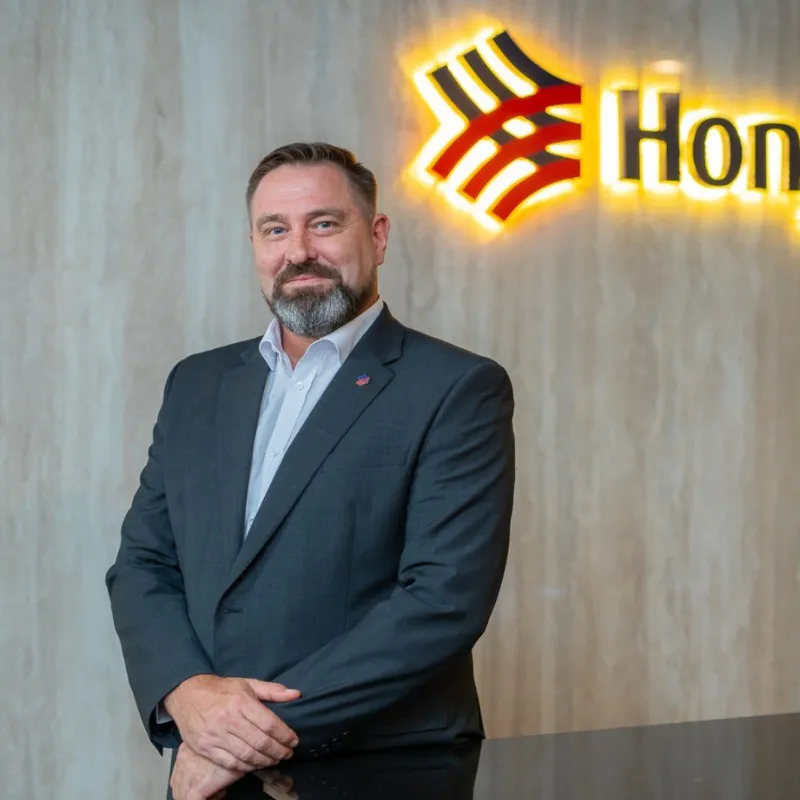
Speaking at Red Hat Summit: Connect 2026 in KL, William Streitberg, chief information and technology officer at Hong Leong Bank, said the financial institution had “made a conscious decision a decade ago” to move away from proprietary systems partly to avoid vendor lock-in and improve its ability to scale.
“So, we were running on a lot of (IT) that were monolithic, and they were vertical (top-down integrated silos). We looked at a number of options and I think Red Hat was where we landed on primarily because they are open source.”
Red Hat was helpful during what William called the bank’s early journey. “We made the strategic choice to be digital at the core,” he said, adding that this led to them building 28 applications “from scratch” with its centre of excellence (COE), on the Red Hat platform.
He described the virtualisation capability Red Hat offered allowed the bank to basically experiment and “fail fast” without the tedious process of contracting and vendor engagement.
Non-proprietary and stable
The move away from proprietary was not just for software. The environment Red Hat enabled meant the bank could scale IT resources up or down, and even add commodity hardware if required.
He also held a pragmatic view towards availability. “We live with the fact that yes, things do go wrong, but the ability to recover using the Red Hat platform has really, really helped.”
High stability numbers were attributed to an architecture that supports multi-nodal clusters to absorb failures seamlessly.
William also frames generative AI as hyper-automation, a capability to bridge siloes, extract meaning from unstructured data and streamline complex processes across back-end processing and customer interactions.
“AI is hyper-automation. It doesn’t need structured data. It doesn’t need a form factor. So it can really, really act as a bridge between multiple data sets… documents… [and] departments.
The GPU challenge – cost, supply and virtualisation
Hong Leong began preparing years ago by building its data lake and early AI experiments.
“We were actually one of the first banks to actually dabble in AI (via) a chatbot on our website powered by AI,” William said.
The bank had also predicted AI was going to develop in a big way. “About three years ago, we predicted this was coming. So we built up our data lake. We built up our data repositories. That was all done. At that point in time, we went and secured some GPU.”
It now operates a small set of on-prem GPUs and is planning to scale. The experience also prompted William to flag two major constraints facing enterprises: acquisition cost and the early stage of on-prem GPU virtualisation.
Hyperscalers have long virtualised GPUs. For sovereign, on-premise deployments however, William admitted “we’re not there yet. We’re still running it bare metal.”
William explained that dedicating a GPU to a model can leave capacity underused. Hence, the bank’s approach is to virtualise GPUs so models don’t tie up hardware inefficiently.
“We want to string all five (GPUs) together, and we want to be able to virtualise those,” he explained.
Guardrails, regulation and the human-in-loop
Despite the promise of automation, William is cautious about ceding decision-making to machines in core banking functions. Regulatory requirements, governance and the imperative to keep customers’ money safe mean human oversight remains essential.
While he recognises AI’s ability to consolidate, interpret, and reason over information, William is more cautious about letting AI agents take actions in a regulated industry like banking. “I think action to (let AI) take an action is not going to go so fast.”