Join our community and be part of the conversation.
To subscribe, simply enter your email address on our website or click the subscribe button below. Don't worry, we respect your privacy and won't spam your inbox. Your information is safe with us.
Verifying AI agents – and the people behind their actions
Risk-based identity checks are becoming essential to building trust at scale, enabling AI agents to assist customers while ensuring critical transactions remain subject to human authorisation.
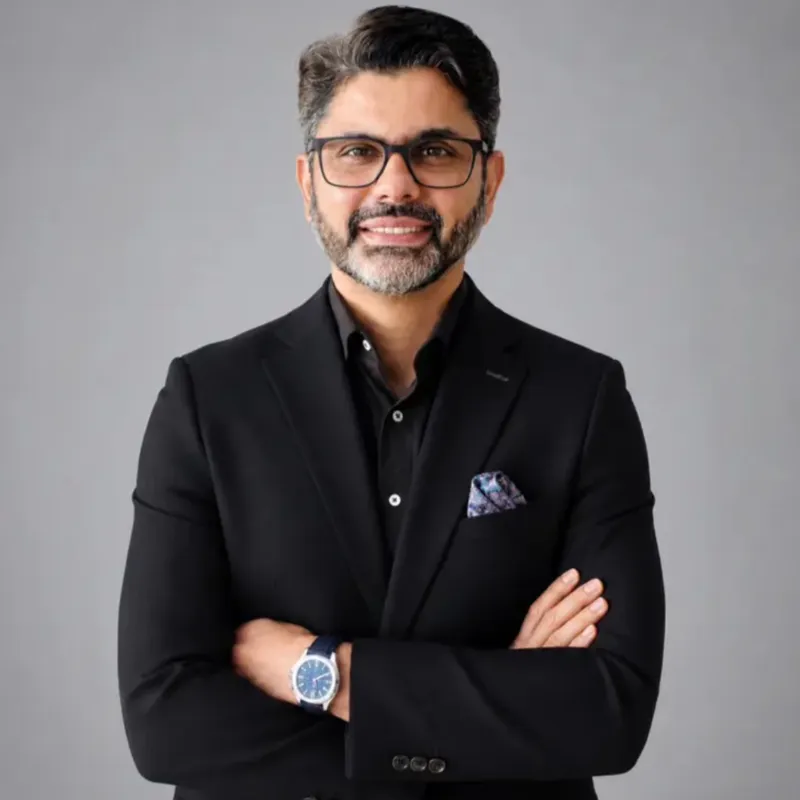
Ping Identity’s Akkasha Sultan said risk signals can trigger additional identity authentication during a financial-services customer journey, bringing a human back into the authorisation process before a critical transaction is completed.
He explained how agent verification and identity controls can be built into a customer journey – especially when an agent’s work leads to a high-stakes action in a regulated industry like financial services.
Akkasha Sultan
How complex can the customer journey get and how many agents will it require?
During the interview with Enterprise IT News, the Asia Pacific and Japan SVP and general manager shared about a US-based lending institution’s advisory AI that uses agents for different tasks:
“There are agents which are collecting information and putting it into an advisory portion,” he said, while another agent helps provide recommendations and “somebody else” pushes actions into core systems.
According to him, the use of agentic technology can potentially deliver 30- to 40-percent productivity gains in information collection and preparation.
Identifying agents
The challenge is ensuring that agents are identified, authorised and limited to their assigned roles. “Customers are asking questions like, who are my agents, what are they supposed to do, what permissions have been granted to them?” he said, describing the queries that surface as customers adopt AI agents technology.
Ping Identity’s approach, as Akkasha described it, is to monitor the journey and use risk signals to determine when additional checks are needed. If a customer or agent initiates a critical transaction, the system can step up authentication and bring the human back into the authorisation process before the action is completed.
“Depending on the triggers from the risk signal, you step up the dynamic authorisation and authentication,” he said. He added that the goal is for agents to act on a person’s behalf while maintaining controls over access and critical actions.
Biometrics as an additional checkpoint
According to Akkasha verification is an ongoing part of the journey, rather than a one-time login check: identify the agent, constrain its permissions, monitor activity, and re-verify the customer when risk signals call for it.
For example, Ping Identity’s Verify product can support additional identity checks using server-side biometrics. He said the technology does not store a customer’s facial image, but creates what he called a “cryptic image” on a server. He also said it can assess liveness and is designed to guard against AI deepfakes and impersonation.
In financial services, Akkasha sees agentic AI adoption as gradual, with organisations first using agents for lower-risk tasks while they build confidence in delegating more consequential actions.
Trusting AI agents
“There are very few customers per se which are performing complete actions using AI agents,” he said, noting that customers are at different stages. But the industry is moving in the right direction, according to the APJ chief, who added that “Ping Identity is helping its customers know the agent that is taking action, defining what the agent can do, and ensuring accountability.”
He concluded that with AI moving from answering questions to taking action, the changing trust equation means the ultimate winners are not necessarily those who move fast, but those “who can earn the trust to operate at scale.”
Cat Yong is Editor-in-Chief of Enterprise IT News, a regional news website which began in Malaysia circa 2011. A common theme in all of her work - opinions, analysis, features and more - is how technology and innovation drives business and outcomes.
A career tech journalist for over 20 years.